April 18, 2024
Budgeting Hacks: How to Take Control of Your Finances
Learn how to budget and invest effectively with our detailed guide. Perfect for individuals looking to enhance their financial literacy.
Read more
A fund manager change rarely makes headlines for retail investors.
There is usually no dramatic change to the fund's name, category or investment objective. Your SIP continues as usual, the NAV keeps moving and your investment platform may not send you a prominent alert.
But in an actively managed mutual fund, a change in the person managing the portfolio deserves attention.
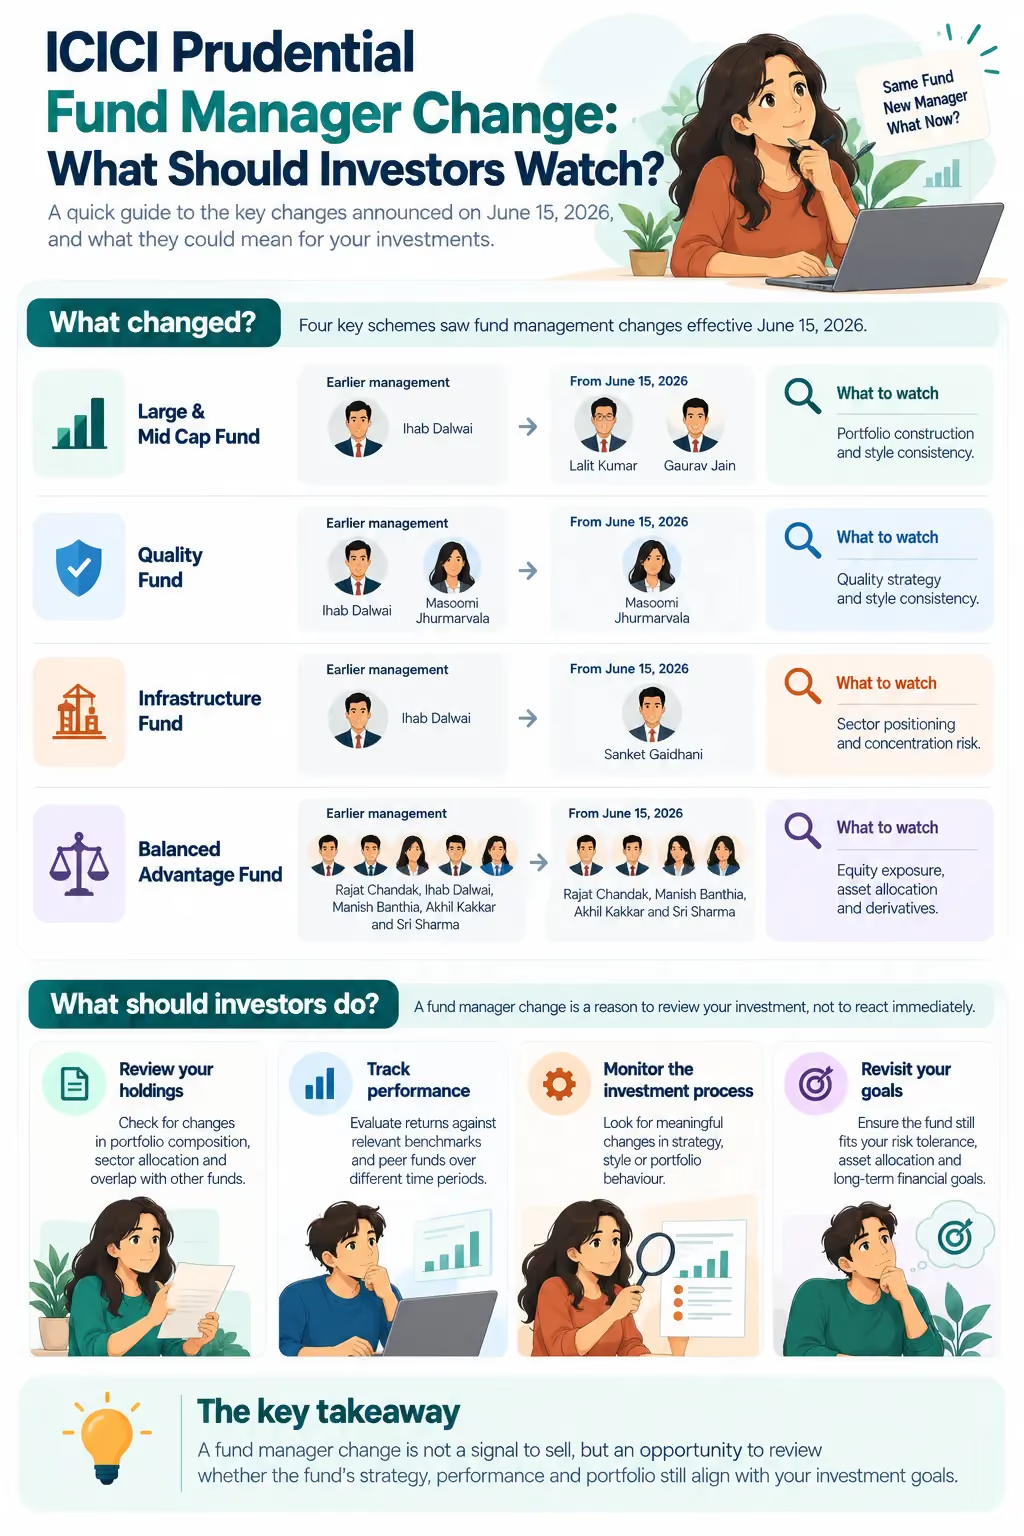
ICICI Prudential Mutual Fund announced several fund-management changes effective June 15, 2026. Among the prominent schemes affected were ICICI Prudential Large & Mid Cap Fund, ICICI Prudential Quality Fund, ICICI Prudential Infrastructure Fund and ICICI Prudential Balanced Advantage Fund.
The changes are worth examining not because a fund-manager change automatically means something is wrong, but because the fund manager is an important part of how an actively managed mutual fund is implemented.
At the same time, it is important not to oversimplify the issue. The fund manager is not the entire product. Investment committees, research teams, quantitative models, investment philosophy and the broader AMC framework can all influence a scheme's portfolio.
That distinction becomes particularly important in the case of the Balanced Advantage Fund.
The June 15 changes included:
The wider disclosure also covered other schemes and strategies, including the Multi Asset Fund and Conglomerate Fund.
This is important because the changes do not represent one uniform event.
In some schemes, there was a new manager coming in. In others, an existing manager remained while another manager exited. The Balanced Advantage Fund retained most of its existing management team.
Therefore, investors should look beyond the headline "fund manager changed" and examine exactly what changed.
Think of an actively managed mutual fund like a restaurant.
The menu tells you what type of food the restaurant serves. But the chef decides which ingredients to use, how much of each ingredient to use and how the final dish is prepared.
A mutual fund's Scheme Information Document defines the mandate. But the investment team determines how that mandate is translated into an actual portfolio.
A manager can influence:
Therefore, a manager change can eventually result in a change in portfolio behaviour.
But the comparison has an important limitation.
At a large AMC such as ICICI Prudential, the investment process is not necessarily dependent on one individual. Research analysts, fund managers, investment committees and quantitative frameworks can provide continuity when an individual manager changes.
The real question is therefore not simply:
"Has my fund manager changed?"
It is:
"Has the investment process that made me choose this fund changed?"
One of the most useful ways to examine the impact of a fund-manager change is to look at both performance and AUM.
The four affected schemes have very different AUM profiles.
The Large & Mid Cap Fund had an AUM of approximately ₹22,857 crore in June 2025. By July 2026, this had increased to around ₹32,706 crore, representing growth of roughly 43%.
That is substantial AUM growth.
However, recent performance has been considerably weaker than its longer-term record. Its one-year return around June 2026 was approximately flat, while its three- and five-year annualised returns remained much stronger.
This tells us something important.
AUM growth does not automatically mean performance is improving.
AUM can increase because of fresh SIP inflows, new investments and market appreciation even when recent returns are disappointing.
For investors, the important question is whether the fund's portfolio and investment process remain consistent with its stated strategy after the management change.
The Infrastructure Fund presents a different case.
Its AUM was approximately ₹8,043 crore in June 2025 and around ₹8,558 crore by August 2026.
The AUM increase was therefore relatively modest compared with the Large & Mid Cap Fund.
The fund's long-term performance record has historically been strong, but infrastructure stocks have also experienced significant cycles. A strong historical return therefore does not mean that future returns will necessarily remain equally strong.
Sanket Gaidhani took over the fund-management responsibility following the change.
For investors, the key question is not simply whether the new manager produces higher returns immediately.
Infrastructure is a concentrated thematic category. The manager's decisions around valuations, sector allocation and individual stocks can have a significant impact on volatility.
Therefore, this is a fund where portfolio changes and risk management deserve close monitoring.
The Quality Fund is a particularly interesting case because the management change did not represent a complete replacement.
The fund originally had Ihab Dalwai and Masoomi Jhurmarvala as managers. Following the change, Masoomi Jhurmarvala remained as the manager.
The fund's AUM was approximately ₹1,933 crore in June 2025 and had risen to around ₹2,144 crore by August 2026.
That represents moderate AUM growth.
The continuity of an existing manager is important because investors are not dealing with a completely new investment decision-maker.
The fund's recent returns have been subdued, but that alone should not be interpreted as evidence that the management change has damaged the fund. Quality-oriented strategies can go through periods when the stocks they favour lag the broader market.
For investors, style consistency may be more important than a few months of performance.
The Balanced Advantage Fund deserves particular attention, but for a different reason.
A BAF does not simply select stocks.
It can dynamically adjust its equity and debt allocation depending on market valuations and other investment signals. ICICI Prudential's BAF has historically used a valuation-driven approach to determine its equity allocation.
This means that investors should consider not only which stocks the manager buys, but also how the fund manages its overall equity exposure.
However, it would be incorrect to describe the June 2026 change as a complete replacement of the BAF's decision-maker.
Ihab Dalwai exited the management team, but Rajat Chandak, Manish Banthia, Akhil Kakkar and Sri Sharma remained.
The change is therefore better understood as a change in the composition of the management team, rather than a complete change in investment leadership.
The fund's scale makes this particularly important.
Its AUM increased from approximately ₹62,014 crore in June 2025 to around ₹74,555 crore by July 2026 — roughly 20% growth.
Managing a ₹75,000-crore-plus portfolio is very different from managing a small fund. Large asset bases can create challenges around liquidity, market impact, derivatives positioning and asset allocation.
For BAF investors, the key metrics to monitor are therefore:
A BAF should not be judged simply by whether it beats the Nifty in a particular year. Its purpose is also to manage the investor's journey through different market environments.
Investors often make the mistake of treating rising AUM as proof that a fund is doing well.
It isn't.
A fund's AUM can increase for several reasons:
Market appreciation + fresh inflows = higher AUM
Similarly:
Market correction + investor redemptions = lower AUM
This creates four broad situations.
This is why AUM should be analysed alongside performance rather than in isolation.
For a manager-change situation, investor flows can also provide a useful secondary signal. Persistent outflows after a management change may indicate declining investor confidence, although flows alone should never determine an investment decision.
Instead of immediately redeeming, investors should track seven things.
Compare the portfolio before and after the management transition.
Have the top holdings changed substantially?
Has the new manager increased exposure to particular sectors?
A meaningful shift could indicate a change in investment style.
Has the fund become more concentrated?
A higher-conviction portfolio may potentially deliver stronger returns, but it can also increase downside risk.
A significant increase in turnover can indicate that the new manager is repositioning the portfolio.
That is not necessarily negative, but it is worth understanding why.
Do not judge the manager based on one quarter.
Look at how the fund behaves during rising, falling and sideways markets.
Is the fund continuing to attract money?
Or are investors steadily redeeming?
AUM trends can provide useful context, although they should not be treated as proof of investment quality.
Finally, ask whether the actual portfolio still resembles the investment strategy you originally bought.
This is perhaps the most important test.
Not automatically.
A fund-manager change is a reason to review your investment, not an automatic reason to redeem.
Investors should also avoid judging a new manager on just two or three months of returns. Short-term performance can be dominated by market movements, sector cycles and valuations.
Give the new management structure several quarters to demonstrate how it manages the portfolio, while continuing to monitor portfolio changes and risk.
There can, however, be legitimate reasons to reconsider a fund.
For example:
These are stronger reasons to reconsider an investment than the manager's name appearing in a disclosure.
The ICICI Prudential fund manager changes illustrate an important point about actively managed mutual funds.
The manager matters, but the manager is not the entire investment process.
A large AMC can have an established research framework, investment committee, quantitative models and multiple managers supporting a scheme.
The impact of a management change will therefore depend on the structure of the individual fund.
For the Large & Mid Cap Fund, investors should watch whether the new management team introduces meaningful changes to portfolio construction.
For the Infrastructure Fund, the focus should be on sector positioning, valuation discipline and concentration risk.
For the Quality Fund, the presence of an existing manager provides greater continuity.
For the Balanced Advantage Fund, investors should pay particular attention to asset allocation behaviour because the fund's role extends beyond stock selection.
Most importantly, do not confuse AUM growth with investment performance. AUM growth can reflect investor inflows and market appreciation, while performance must be evaluated against the fund's benchmark, category and stated objective.
The right response to a fund-manager change is therefore neither panic nor complacency.
It is review.
A manager change should prompt investors to revisit the fund's investment philosophy, portfolio construction, performance, AUM trends and risk profile.
If the underlying investment thesis remains intact and the new management structure is credible, there may be no reason to exit.
If the portfolio begins to show persistent style drift, rising risk or deterioration in the investment process, a reassessment may be warranted.
A fund-manager change is a trigger to investigate — not a signal to automatically sell.
Schedule a call based on your convenience. And get an expert to help you invest.

The financial life game that makes learning fun!
Let's get in touch
Want the best
investment blog delivered straight to your inbox?
Grow your money without wasting time
on stock picking, poring over excel sheets, financial news, analyzing market trends, tracking the Sensex, researching company fundamentals, comparing mutual funds, reading financial reports, trying to predict the future & losing your sanity!