Choice Bracketing in Behavioural Finance: Why Evaluating Investments One by One Can Hurt Your Portfolio
Discover how choice bracketing bias affects investment decisions and why evaluating your entire portfolio—not individual investments—can improve diversification, manage risk, and support your financial goals.
Investors often evaluate investments one at a time.
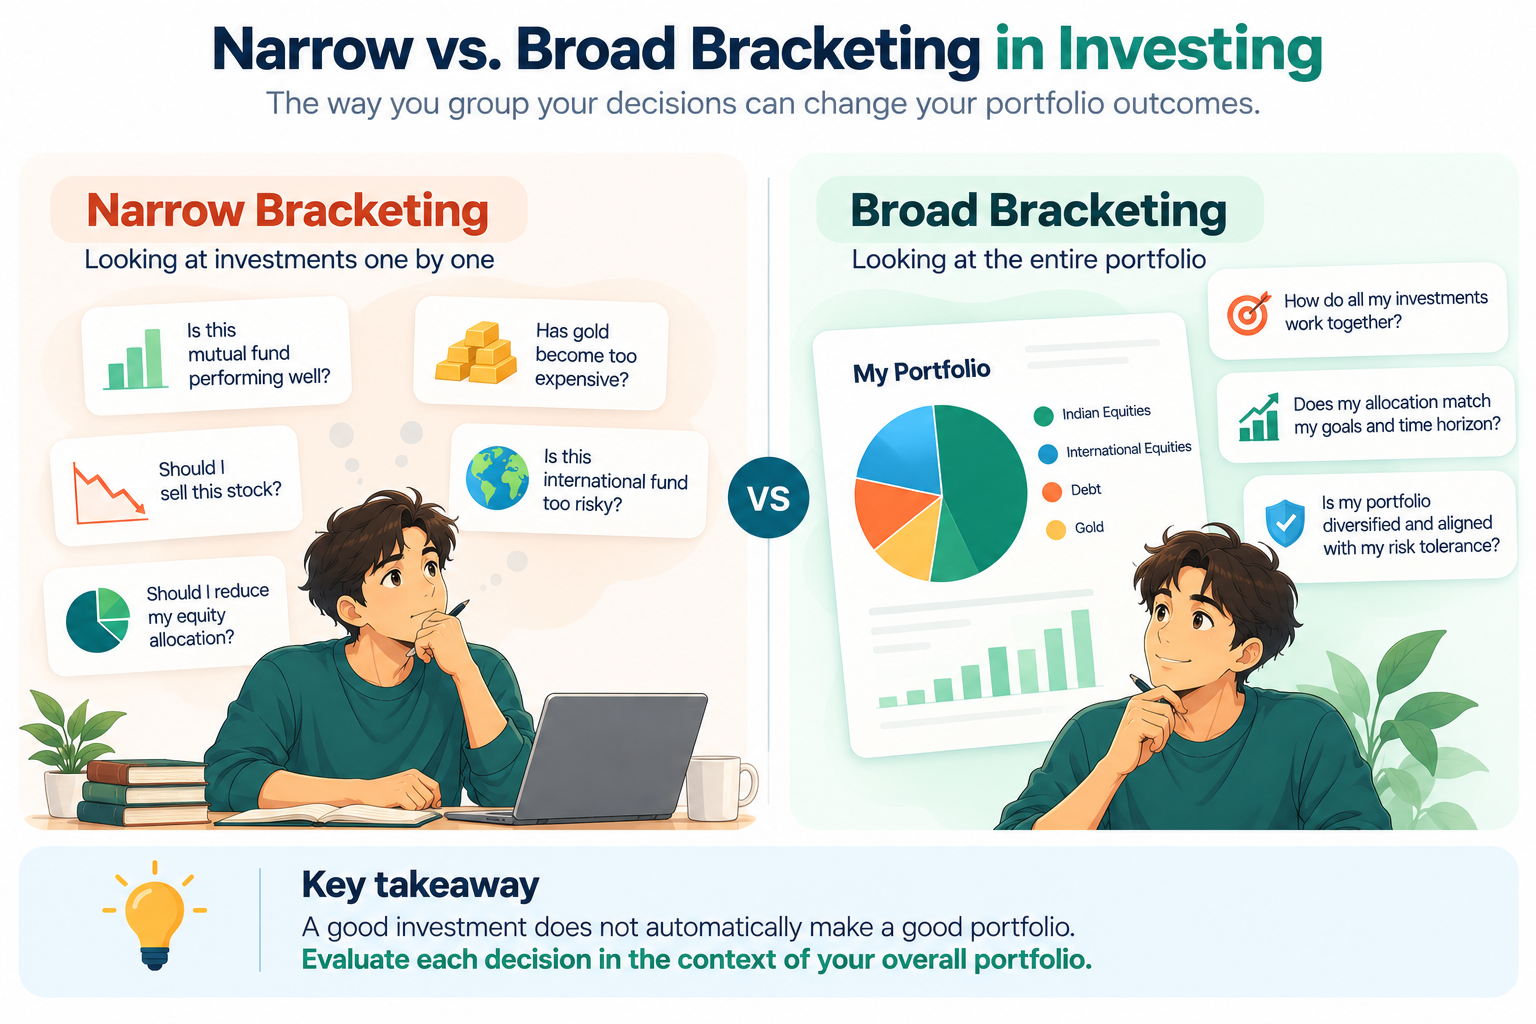
Is this mutual fund performing well? Should I sell this stock? Has gold become too expensive? Should I reduce my equity allocation? Is this international fund too risky?
Each question seems reasonable when considered on its own. But investing is rarely about individual investments. What matters is how those investments work together as a portfolio.
This is where choice bracketing in behavioural finance becomes important.
Choice bracketing describes how people group decisions before making them. With narrow bracketing, decisions are evaluated separately. With broad bracketing, several decisions are considered together and judged based on their combined outcome.
In investing, narrow bracketing can cause investors to focus too much on individual investment performance and overlook the bigger picture: diversification, concentration, asset allocation and overall portfolio risk.
The result can be a portfolio that looks sensible investment by investment but makes little sense when viewed as a whole.
What Is Choice Bracketing in Behavioural Finance?
In simple terms, choice bracketing is the way we group our decisions.
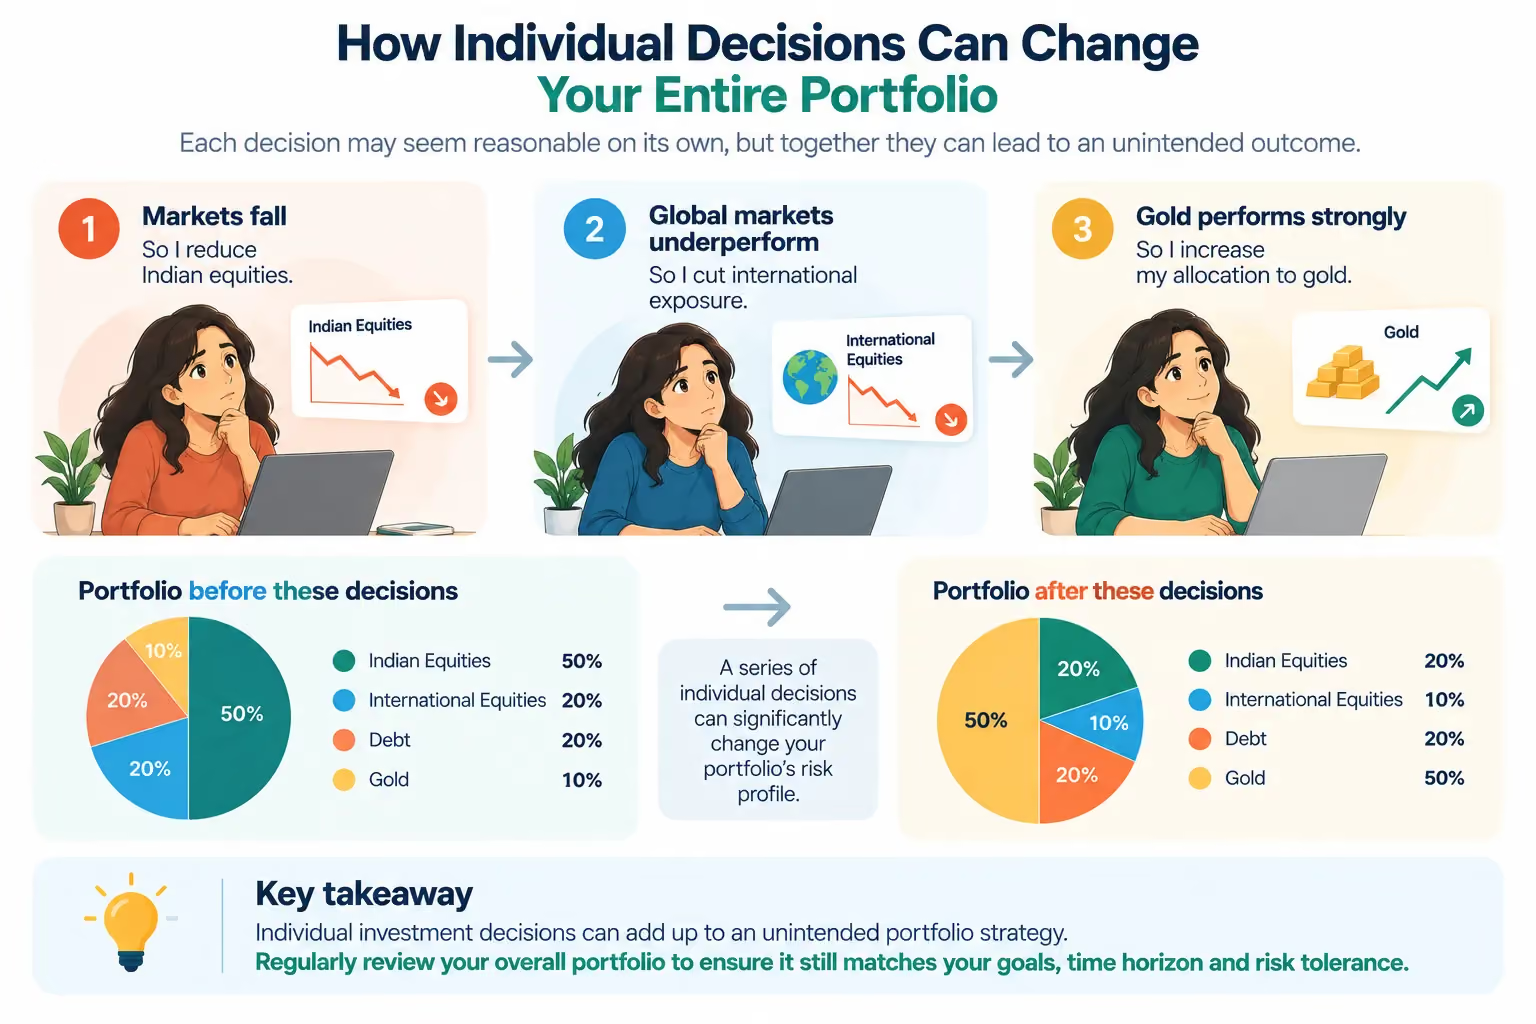
Imagine an investor owns Indian equities, international equities, debt and gold.
The stock market falls, so the investor reduces Indian equities. International markets subsequently underperform, so the investor cuts global exposure. Gold performs strongly, so the investor increases the allocation to gold.
Every decision may appear logical when looked at individually.
But taken together, these decisions may have changed the portfolio from a growth-oriented portfolio into a much more defensive one.
The investor may not have consciously decided to make such a large change in risk. It happened through a series of individual decisions.
This is narrow bracketing.
A broader approach would ask:
“What has happened to my overall portfolio, and does it still match my goals, time horizon and risk tolerance?”
That is broad bracketing.
Research in behavioural economics has found that people frequently make decisions using narrow rather than broad brackets. Studies have also examined how this tendency can affect financial decisions and portfolio allocation.
Why Do Investors Evaluate Investments One by One?
Looking at investments individually is simply easier.
Investors naturally pay attention to things that are easy to see:
A mutual fund that has fallen 12%
A stock that has doubled
Gold that has recently performed strongly
An investment that has lagged its benchmark
A portfolio holding that has generated disappointing returns
Recent performance can therefore become the basis for a decision.
But investment performance and portfolio performance are not always the same thing.
An investment that has underperformed may still have an important role in diversification. Another investment that has delivered excellent returns may have made the portfolio excessively concentrated.
This is why behavioural biases in investing can affect decisions even when investors believe they are being rational.
A Simple Example Outside Finance
Consider someone trying to eat healthier.
On Monday, they eat a burger after a stressful day. On Wednesday, they have dessert at a celebration. On Friday, they order pizza with friends. On Sunday, they skip exercise because they are tired.
None of these decisions is particularly alarming on its own.
The narrow-bracketing approach asks:
“Is it okay to have this burger today?”
“Is one dessert really a problem?”
“Can I skip exercise today?”
A broader approach asks:
“What do my food and exercise choices add up to over the entire week?”
The second question gives a much better picture of the outcome.
Investment decisions work in a similar way.
Selling one investment after a market fall may not seem significant. Increasing another after it performs well may also appear reasonable. But several such decisions can collectively change the risk and diversification of the entire portfolio.
How Does Choice Bracketing Affect Investment Decisions?
The biggest problem with narrow bracketing is that it can make investors focus on the quality of individual investments rather than the quality of the combination.
Consider two investments.
Investment A has delivered strong returns but owns many of the same companies as other investments already in the portfolio.
Investment B has been more volatile and has delivered lower returns, but its underlying exposure is very different from the rest of the portfolio.
Viewed individually, A may look more attractive.
Viewed as part of the portfolio, B may contribute more to diversification.
This is an important distinction.
A good investment does not automatically make a good addition to a portfolio.
The question should not simply be:
“Is this a good investment?”
It should be:
“Does this investment make my overall portfolio better?”
More Investments Do Not Always Mean More Diversification
One common consequence of narrow investment decisions is owning too many similar investments.
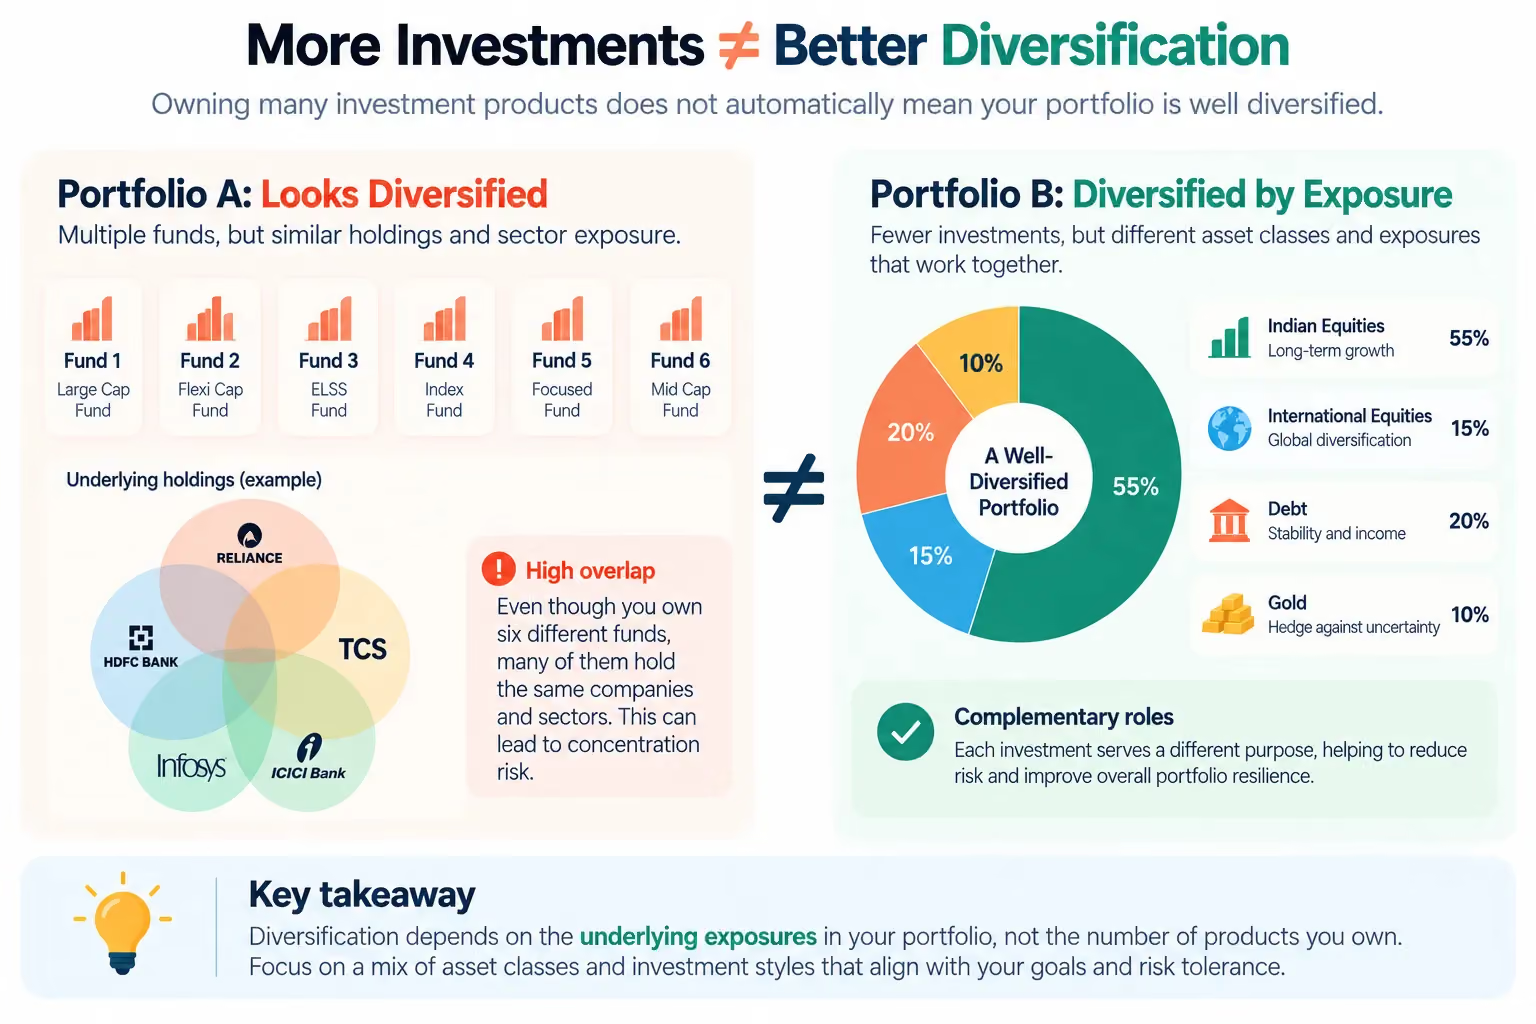
An investor may hold six equity mutual funds and assume that the portfolio is well diversified.
But if several funds own similar companies, sectors or themes, the actual diversification may be much lower than it appears.
The same principle applies across asset classes.
An investor may have several investments that appear different on the surface but are all exposed to the same underlying economic or market risk.
Therefore, portfolio diversification is not simply about the number of investments you own. It is about how different those investments are and how they behave together.
A diversified portfolio should be assessed by its overall exposures, rather than simply counting products.
Why a Volatile Investment Is Not Always a Bad Investment
This is another area where looking at investments individually can be misleading.
It may look like the obvious investment to remove.
But what if that investment behaves differently from the rest of the portfolio?
Its behaviour may actually provide diversification.
Conversely, an investment that has performed extremely well may increase the portfolio's concentration if it becomes too large.
This is why portfolio risk cannot be understood simply by looking at the volatility of individual investments.
The interaction between investments matters.
How Can Investors Avoid Choice Bracketing Bias?
You do not necessarily need a financial advisor to reduce this behavioural bias. The most important change is to develop a habit of looking at decisions in the context of the entire portfolio.
1. Decide your asset allocation before choosing investments
Start with the bigger picture.
Think about how much of your portfolio should be allocated to different types of assets based on your goals, investment horizon and ability to tolerate risk.
Then select investments to fill those roles.
This is more effective than accumulating investments first and trying to work out the portfolio structure later.
2. Review the portfolio, not just individual investments
When reviewing your investments, don't only ask:
“Which fund performed best?”
Also ask:
What percentage of my portfolio is in equity?
How much is exposed to one sector?
How much is invested internationally?
How much is relatively stable?
Have any holdings become disproportionately large?
Has my overall risk changed?
This shifts the focus from investment performance to portfolio health.
3. Look through the investment to the underlying exposure
Two mutual funds with different names are not necessarily two different sources of diversification.
Look at their underlying holdings, sectors, geographies and investment styles.
The objective is to understand what risks you actually own.
4. Give every investment a role
Before buying an investment, identify why it belongs in the portfolio.
Is it there for:
Long-term growth?
Stability?
Income?
Diversification?
Exposure to a particular market?
A specific financial goal?
If you cannot explain the role of an investment, it may deserve a closer look.
5. Don't confuse recent performance with a change in fundamentals
One of the easiest ways to fall into narrow decision-making is to react to recent returns.
A fund underperforms for six months and suddenly appears unsuitable. Another investment rallies for a year and suddenly appears essential.
Before making a change, ask:
“Has something fundamentally changed, or am I simply reacting to recent performance?”
6. Set rules for portfolio rebalancing
Instead of changing your portfolio every time markets move, establish a review process.
For example, you could review your asset allocation periodically and consider rebalancing when allocations move significantly away from your intended levels.
Having a rule reduces the influence of short-term emotions on investment decisions.
7. Use a cooling-off period for major decisions
If you suddenly feel that an investment must be sold because markets have fallen sharply, pause.
Write down:
Why you want to sell
What has changed
What you will buy instead
How the change affects your overall portfolio
Whether the decision changes your original investment plan
This simple process can help separate a considered decision from an emotional reaction.
A Simple Portfolio Test
Before buying or selling an investment, ask these five questions:
1. What role does this investment play in my portfolio?
2. Do I already own something with similar exposure?
3. What will my overall asset allocation look like after this decision?
4. Am I reacting to recent performance?
5. Will this decision improve my portfolio or simply change one investment?
These questions help move the decision from a narrow bracket to a broader bracket.
The Bigger Lesson From Choice Bracketing
Choice bracketing is not about saying that individual investment decisions are wrong.
The problem is that several individually reasonable decisions can sometimes produce an unreasonable overall result.
Think of a cricket team. You don't select every player simply because they are the best individual player. You choose players who perform different roles and work together as a team.
A portfolio works in much the same way.
One investment may provide growth. Another may provide stability. Another may provide diversification. Another may provide exposure to a different geography or asset class.
The objective is not to collect the maximum number of good investments.
It is to build a combination of investments that works towards your financial goals.
That is the central lesson of choice bracketing in investing.
Don't ask only, “Is this a good investment?”
Ask:
“Does this make my portfolio better?”
That small change in perspective can help investors make more rational investment decisions, avoid unnecessary portfolio changes and think beyond the performance of individual investments.
1. What is choice bracketing in behavioural finance?
Choice bracketing is the way people group decisions. Narrow bracketing means evaluating decisions separately, while broad bracketing means considering several decisions together and looking at their combined outcome.
2. What is narrow bracketing in investing?
Narrow bracketing in investing means evaluating investments individually rather than considering how they affect the overall portfolio. For example, selling an underperforming fund without considering its role in portfolio diversification is a form of narrow decision-making.
3. What is broad bracketing in investing?
Broad bracketing means evaluating investment decisions together. Instead of asking whether one investment is performing well, investors consider its effect on overall asset allocation, diversification, concentration and portfolio risk.
4. How does choice bracketing affect investment decisions?
Choice bracketing can cause investors to focus too heavily on individual returns and overlook the interaction between investments. This can result in excessive concentration, duplication of investments or an unintended change in portfolio risk.
5. How can investors avoid choice bracketing bias?
Investors can reduce choice bracketing by reviewing the entire portfolio, setting an asset allocation, understanding underlying holdings, assigning a role to each investment, using rebalancing rules and avoiding impulsive decisions based solely on recent performance.
6. Does owning more investments mean better diversification?
No. Owning more investments does not automatically create better diversification. Several funds or stocks may have similar underlying holdings or exposures. Effective diversification depends on how different investments behave and the risks they add to the overall portfolio.
7. Should I sell an underperforming mutual fund?
Not necessarily. Before selling, consider why the fund was selected, whether its investment strategy has changed, how it fits into the overall portfolio and whether its underperformance is temporary or reflects a fundamental problem.
8. How often should I review my investment portfolio?
There is no universal frequency that works for everyone. The important point is to review the portfolio systematically rather than reacting to every market movement. A periodic review can help identify changes in asset allocation, concentration and risk.
9. Do I need a financial advisor to avoid behavioural biases?
No. Investors can use simple processes such as written investment rules, portfolio reviews, rebalancing thresholds and cooling-off periods. An advisor can provide an independent perspective, but the basic principle of looking at the portfolio as a whole can be applied independently.
10. What is the key lesson from choice bracketing?
The key lesson is to evaluate investments based on their role in the overall portfolio, rather than judging them only on standalone performance.
The right question is not “Is this a good investment?” It is “Does this investment make my overall portfolio better?”
Barun is an experienced wealth management professional with over 13 years of expertise in guiding individuals and institutions on their investment journeys. He possesses a deep understanding of financial markets, encompassing a wide range of products, including mutual funds, stock advisory, complex structured products, forex, bonds, and corporate NCDs. He is NISM VA and XXI A certified, as well as IRDAI certified for insurance.
Schedule a call based on your convenience. And get an expert to help you invest.
on stock picking, poring over excel sheets, financial news, analyzing market trends, tracking the Sensex, researching company fundamentals, comparing mutual funds, reading financial reports, trying to predict the future & losing your sanity!
Thanks For Subscribing!
We'll send you interesting emails about exciting investment options.
Oops! Something went wrong while submitting the form.
Upload your mutual fund statement for tailored recommendations and a comprehensive portfolio review.
Upload Your Consolidated Account Statement from CAMS
We'll email your personalised mutual fund review in a few days—our experts, who have 40+ years of experience, go beyond quick algorithms to deliver deep, customised insights.
To get recommendations aligned with your goals, fill out your risk profile here.
For any questions, feel free to reach us at wealth@bankoncube.com
How to Download Your Consolidated Account Statement (CAS)